Tanning Salon Memberships: EFT Billing and Self-Serve Beds
Set up tanning salon membership billing that holds up: card vs. ACH dues, freeze and cancel terms, failed-payment recovery and after-hours bed access.
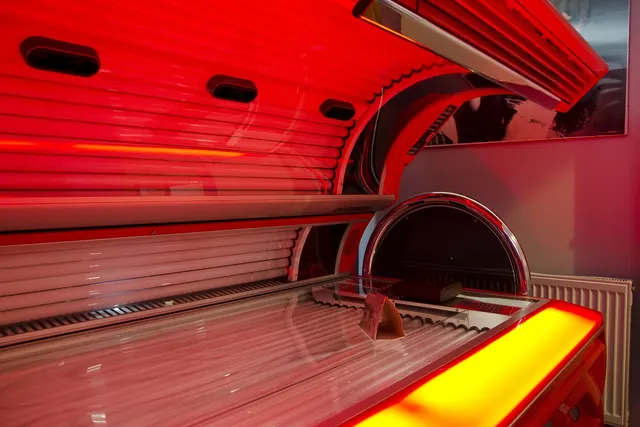
Photo: Pixabay
On this page 6 sections
- Tanning Salon Membership Billing: Monthly EFT vs. Session Packs
- Card vs. ACH for Tanning Salon EFT Dues
- Write Freeze and Cancellation Terms Into the Agreement
- Self-Serve Tanning Kiosk Payment and After-Hours Beds
- Reducing Failed Payments in Unlimited Tanning Autopay
- Tanning Salon Software Payments: What to Ask Before You Sign
Key takeaways
- Collect a card and a bank account at signup, and authorize both in the agreement so the backup method can actually be charged.
- Card fees usually scale with the dues price while ACH is often a flat fee per debit. The case for ACH gets stronger on premium tiers, so run the math on your own statement.
- After-hours beds need billing checks in real time. Without them, a declined member keeps tanning until someone notices.
- Tell your processor before you add an unattended kiosk, because self-serve card acceptance is set up differently from a front-desk terminal.
Tanning salon membership billing holds up when the member signs a clear monthly agreement and the payment method on file keeps working. It also depends on software that ties billing status to bed access in real time. If one piece fails, you spend Mondays chasing declines and arguing about cancellations. Then you find out a lapsed member tanned free all weekend on the after-hours beds.
In tanning, "EFT" (electronic funds transfer) usually means any automatic monthly draft, whether it runs on a card or as an ACH debit from a checking account. A single-location salon and a multi-location franchise face the same decisions, and the first one is what you sell.
Tanning Salon Membership Billing: Monthly EFT vs. Session Packs
Most salons sell prepaid packs alongside unlimited monthly memberships, and walk-ins buy single visits on top of that. Unlimited plans are usually tiered by bed level. A basic-bed plan sits at the bottom, and high-pressure beds or sunless spray are priced as a higher tier or as a per-visit upgrade.
Packs bring cash in up front, but every unused session is a service you still owe. They also sell in seasonal waves before prom and spring break. Unlimited memberships smooth that out because members keep paying through the slow months. The catch is that the slow months are also when members ask to freeze or cancel, so your billing setup has to handle both without staff improvising.
Settle these billing choices while you design the plans, not after:
- Draft date. Billing everyone on the 1st is simple to reconcile. Billing each member on their signup anniversary spreads declines across the month, so one bad day doesn't drain cash flow.
- First-month proration. On a 1st-of-month schedule, decide whether a mid-month signup pays a partial month or a full one, and print the answer on the agreement.
- Upgrade charges. A basic member who wants a premium bed can have the upgrade charged to the card on file automatically or pay at the desk or kiosk. Automatic is convenient, but it produces more "I didn't authorize this" calls when statements arrive.
- Minimum term. Month-to-month plans sell more easily. A commitment period reduces churn but needs tighter disclosures, which come up again in the cancellation section below.
Card vs. ACH for Tanning Salon EFT Dues
A card is easier to collect because the member taps or types it at signup. ACH usually costs less per draft, but it needs bank account details and a signed authorization. The ACH network's operating rules, written by Nacha, require the customer's authorization for recurring debits. Consumers can also return a debit they say they didn't authorize. Your bank or processor sets the return fees and timing that apply to you.
The two rails are priced differently. Most card pricing combines a percentage of the sale with a per-transaction fee, so the cost of each draft rises with your dues price. ACH debits are commonly priced as a flat fee. As a result, the gap between them widens on premium tiers and narrows on a cheap basic plan. A salon whose members mostly pay for a top-tier bed has more to gain from ACH than one selling entry-level unlimited.
Run the Card-vs-ACH Math on Your Own Numbers
Generic rate quotes won't tell you much, because your card mix drives the real cost. Rewards and business cards cost more to accept than basic debit. Work from your own statement instead:
- Find your real card cost per draft. Take last month's processing fees on recurring dues and divide by the number of drafts. That figure already reflects your actual card mix.
- Get two ACH numbers from your processor: the fee per debit and the fee per returned debit.
- Estimate returns. If you already draft by ACH, pull your return count. If not, ask your processor what it typically sees on consumer recurring debits.
- Compare the totals. Card cost equals drafts times your card cost per draft. ACH cost equals drafts times the ACH fee, plus returns times the return fee.
- Add what a return really costs. A returned debit also means dues you don't collect until the member gives you a new account, and sometimes never. A closed bank account gives you no warning. Card networks, by contrast, run account updater services that can refresh a reissued or expired card automatically.
For most salons the answer is to collect both at signup. Make ACH the default, or price it a little lower where state law and your processor agreement allow. Keep a card on file as a backup that the agreement explicitly authorizes you to charge. If you'd rather offset card costs on dues than steer members away from cards, look at dual pricing and cash discount programs from MannyPay, and confirm the disclosure requirements for recurring charges before you change anything.
Write Freeze and Cancellation Terms Into the Agreement
The typical membership fight goes like this: the member believes they canceled, and the salon has no record of it. The issuing bank then decides who's right. A dispute coded as a canceled recurring transaction is hard to win unless you can show the member agreed to specific terms and didn't follow them.
Put your freeze policy in the agreement in plain language:
- Maximum freeze length, and how many freezes a member can take per year.
- Freeze fee, if you charge one. A small monthly hold fee keeps the payment method active and the member in your system. Disclose it at signup rather than when someone asks to freeze.
- What happens to the draft date. State whether billing resumes on the original date or shifts by the length of the freeze.
- How to request one. Name the channels that count and the notice you need before the next draft. If members can join online, letting them freeze online heads off the "but I emailed you" argument.
Cancellation terms need the same precision. Spell out how a member cancels and how much notice you require. Say whether the current month is refunded, along with anything that ends a commitment term early. A move beyond a set distance from the salon is a common example.
State Auto-Renewal Laws and Card Network Rules
Many states have automatic renewal laws. In general they require clear disclosure of renewal terms before the customer signs, plus the customer's affirmative consent to those terms. Several also require a cancellation method that's reasonably easy to use, sometimes through the same channel the customer used to sign up. Federal rules on negative-option billing have shifted in recent years, so check where they stand when you update your agreement. Requirements differ by state. Treat this as general information and have an attorney review your membership agreement.
Card networks set their own requirements on top of state law. Visa and Mastercard's free trial and subscription billing rules cover what you must disclose and when, which matters if you run free-week or discounted first-month promotions.
Then keep the evidence. Your software should store the signed agreement with a timestamp and the version of the terms the member accepted. It should also log each freeze or cancel request with the date it arrived. When a dispute comes in, that record is your response.
Self-Serve Tanning Kiosk Payment and After-Hours Beds
After-hours tanning splits into two models: members who already pay by EFT and walk-ins who pay on the spot. Many salons run both.
Member Access Without a Payment on Site
Members scan a key fob or an app code at the door, and the software unlocks a bed timer. Nothing is charged on site, so billing status carries all the weight. The system has to check whether the account is current at the moment of the scan, not from a nightly sync. Gyms face the same problem, and our guide to locking out 24-hour gym members who don't pay walks through the access-control logic.
Kiosk or App Sales for Walk-Ins
A walk-in buys a single session or an upgrade at a kiosk that takes cards and mobile wallets, then gets a code for the bed. MannyPay sells self-service kiosks for unattended payments, including the Clover Kiosk. Whether a kiosk can talk to your bed controllers depends on your tanning software, so confirm that integration before buying hardware. App-based starts cost less to deploy, since the member pays in the salon's app and starts the bed with a QR scan, but they're only as reliable as the app's billing integration.
Unattended card acceptance is set up and processed differently from a staffed terminal. Tell your processor before you add a kiosk or start after-hours sales. It's one of the changes covered in when to tell your payment processor about a business change.
Some operational details turn into payment problems if you skip them. Post a refund and malfunction policy at every bed, because "the bed shut off after four minutes" with nobody on site becomes a chargeback. The kiosk flow also has to capture the consent and skin-type paperwork your state requires. Many states restrict indoor tanning for minors, and an unstaffed sale can't skip those checks. Cameras and access logs help you answer disputes as much as they help with security.
Reducing Failed Payments in Unlimited Tanning Autopay
Involuntary churn means members who would have kept paying, but whose payment failed and was never recovered. It quietly drains unlimited tanning autopay programs because nobody decided to leave.
You can size it in a few minutes. Take last month's declined drafts, subtract the ones you recovered, and multiply what's left by your monthly dues. That's this month's leak. Multiply again by the number of months a typical member stays, and you see what one unrecovered decline really costs.
Most of the fixes are settings, not projects:
- Account updater. Ask whether your processor and software use the networks' updater services so reissued and expired cards refresh on their own.
- Expiring-card notices. Text or email members a few weeks before a card on file expires.
- Retry schedule. Retry declines on a spaced schedule instead of hitting the card daily. Card networks limit repeated attempts on declined transactions and can charge for excessive retries, so ask your processor what rules its retry logic follows.
- Desk and door flags. A failed draft should prompt staff at the member's next visit and block after-hours access until the account is updated.
- Backup method. The second payment method you collected at signup helps only if your agreement authorizes charging it.
Tanning Salon Software Payments: What to Ask Before You Sign
Your software decides how much of this you can automate, so evaluate the billing side as hard as the bed controls. Ask each vendor:
- Does it require its own processor, or can you choose one? Locked-in processing limits your leverage on rates later.
- If you leave, can your card vault be exported to a new processor? Losing stored cards means re-enrolling every member. Our guide to switching salon software without losing clients' saved cards explains what to get in writing.
- Does it support both ACH and card drafts, with a backup method per member?
- Can it automate freezes, freeze fees and draft-date shifts?
- Does access control check billing status in real time?
- Does one report show declines alongside what was recovered?
- Does it support kiosk sales and unattended terminals, and through which gateway?
To benchmark what you pay now, see what a salon should pay for card processing. You can also review how MannyPay works with health and beauty businesses.
Start with your own data this week. Pull last month's decline report and count how many members are still unpaid, then check how many cards on file expire in the next two months. Bring those numbers and your current processing statement when you request a free processing quote. A MannyPay specialist responds within one business day.
This article is for general educational purposes and is not legal, tax or financial advice. Card network rules and state laws change; confirm current requirements for your business.